Loading...

Developing personalized charity journeys to increase donor satisfaction strengthen community trust and expand our humanitarian by global philanthropic.

Top-Up Health Insurance in Mumbai

Get Higher Health Coverage at an Affordable Premium

Top-up health insurance helps increase your medical coverage beyond a specified deductible, making it easier to prepare for costly hospitalisation. It can complement your existing individual, family or employer-sponsored health insurance by providing additional financial protection for eligible medical expenses above the deductible.

Explore top-up and super top-up health insurance options with Niraj Shinde Insurance & Financial Services in Dadar, Mumbai, and understand the coverage, deductible, waiting periods and exclusions before choosing a plan.

Top-Up Health Insurance

What Is Top-Up Health Insurance?

Top-up health insurance is a medical insurance policy designed to provide additional coverage once eligible hospitalisation expenses cross a specified amount called the deductible. It can help protect your savings when medical bills exceed the coverage available under your existing health insurance.

For example, suppose you have a ₹5 lakh base health insurance policy and a super top-up plan with a ₹5 lakh deductible and ₹20 lakh additional sum insured. If your eligible medical expenses exceed the deductible, the super top-up may cover the eligible amount above it, subject to the policy terms and available sum insured.

A regular top-up generally applies the deductible to each individual claim, whereas a super top-up generally considers eligible claims cumulatively during the policy year. Understanding this difference is important when selecting additional medical coverage.

What Does Critical Illness Insurance Cover?

✅  Commonly Covered Conditions

❌  What May Not Be Covered?

Key Benefits of Top-Up Health Insurance

Higher Medical Coverage

Increase your potential protection against large hospital bills without relying solely on your base policy.

Affordable Additional Protection

Top-up plans may cost less than purchasing the same additional amount as a standalone base policy, depending on the deductible and other terms.

Support Beyond Employer Coverage

Supplement workplace health insurance with additional cover, while checking portability, renewal and eligibility conditions.

Protection Against Multiple Hospitalisations

A super top-up plan may consider eligible expenses from multiple hospitalisations within the same policy year when calculating the deductible.

Flexible Coverage Options

Choose a deductible and sum insured based on your existing cover, financial responsibilities and budget, subject to the insurer's available options.

Complementary Health Protection

A top-up plan can work alongside an individual or family health policy to help manage eligible expenses that exceed the base coverage.

Types of Top-Up Health Insurance Plans

Explore top-up health insurance options designed to increase your medical coverage beyond a chosen deductible. Regular top-up plans generally apply the deductible to each claim, while super top-up plans usually consider eligible expenses across multiple claims in a policy year. Choose based on your existing coverage, budget, and healthcare needs.

Regular Top-Up Health Plan

Applies the specified deductible separately to each eligible hospitalisation claim. It may suit people whose main concern is a single large medical bill.

Super Top-Up Health Plan

Considers eligible medical expenses across multiple claims during the policy year when assessing the deductible. It can provide broader protection when several hospitalisations occur in the same year.

Top-Up Plan Alongside Employer Health Insurance

Adds extra protection above your workplace medical coverage. It may help reduce the coverage gap if your employer's policy has a limited sum insured, although you should consider what happens if you change jobs.

Top-Up Plan Alongside Individual or Family Health Insurance

Supplements your existing individual or family floater policy with additional coverage above a selected deductible, helping you increase your overall financial protection.

img Process

How to Choose the Right Top-Up Health Insurance Plan
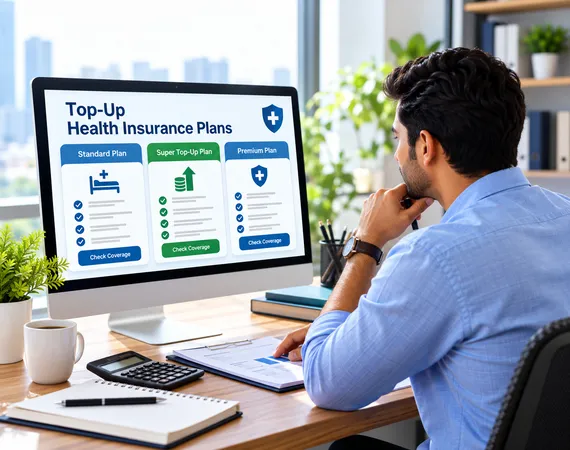
Top-Up Health Insurance plan

01

Assess Your Coverage Needs

Review your existing health insurance, financial responsibilities and potential medical expenses to determine suitable additional coverage.

02

Compare Policy Benefits

Evaluate premiums alongside the sum insured, deductible, sub-limits, waiting periods and exclusions.

03

Evaluate the Insurer

Review claim settlement information, claim procedures and policy disclosure requirements before making a decision.

04

Choose Useful Add-Ons

Consider optional benefits that suit your healthcare needs and compare their advantages with the additional premium.

0 +

Families Supported

0 +

Insurance Partners

0 %

Client Support

Who Should Consider Top-Up Health Insurance?

Top-up health insurance may be suitable for families who want to increase their existing medical coverage, salaried employees seeking additional protection beyond employer-provided insurance, and self-employed professionals planning for unexpected hospital expenses. It can also benefit individuals with financial responsibilities who want to protect their savings from large medical bills, as well as policyholders looking for higher coverage at a potentially affordable premium. The right plan depends on your existing insurance, budget, healthcare needs and the policy’s terms and conditions.

+91 89760 78348

info@nirajishindeinsurance.com

Factors That Affect Your Top-Up Health Insurance Premium

Top-Up Health Insurance Claim Process

Notify the Insurer

Inform the insurer about the hospitalisation and follow the required claim notification process.

Submit Required Documents

Provide the claim form, base policy details, hospital bills and relevant medical records.

Deductible and Claim Assessment

The insurer verifies eligible expenses, deductible requirements and policy conditions.

Claim Approval and Payment

If approved, the insurer pays the eligible amount according to the policy terms and applicable limits.

Frequently Asked Questions About Top-Up Health Insurance

  • 1. What is the main purpose of top-up health insurance?
    It provides additional coverage for eligible medical expenses above a specified deductible, helping supplement your existing health insurance.
  • 2. What is the difference between top-up and super top-up insurance?
    A regular top-up generally applies the deductible to each claim separately. A super top-up generally considers eligible expenses from multiple claims during the policy year when calculating the deductible.
  • 3. Do I need an existing health insurance policy to buy a top-up plan?
    Not necessarily. However, you need to plan how the deductible will be met. Without suitable base coverage, you may have to pay some or all of the deductible yourself.
  • 4. How should I choose the deductible?
    Consider your existing health insurance coverage and how much you could afford to pay if a hospital bill exceeds that coverage. Review the deductible calculation and terms before choosing.
  • 5. Does top-up health insurance have waiting periods?
    Yes, a policy may have initial waiting periods, pre-existing disease waiting periods and other condition-specific requirements. The exact terms vary by insurer and plan.
  • 6. Can I use top-up insurance with employer-provided health insurance?
    It may be possible, subject to the top-up policy's conditions. Check how the deductible is met, which documents are needed and what happens if your employment or employer coverage changes.

Niraj Shinde Insurance & Financial Services offers trusted insurance guidance in Dadar, Prabhadevi and Mumbai, helping individuals and businesses with policy selection, renewals and claim assistance.

Contact

Phone & Email

info@nirajishindeinsurance.com
+91 89760 78348

Office Address:

Shop no. 8, Raj chs, opp. marathe udyog, Century Bazaar, Prabhadevi, Mumbai, Maharashtra 400025

© 2026 Niraj Shinde. Designed & Developed by Peaceinfotech Services Pvt. Ltd.

Policy & privacy / Terms & conditions